Show a new channel’s CPA beside the blended programme cost
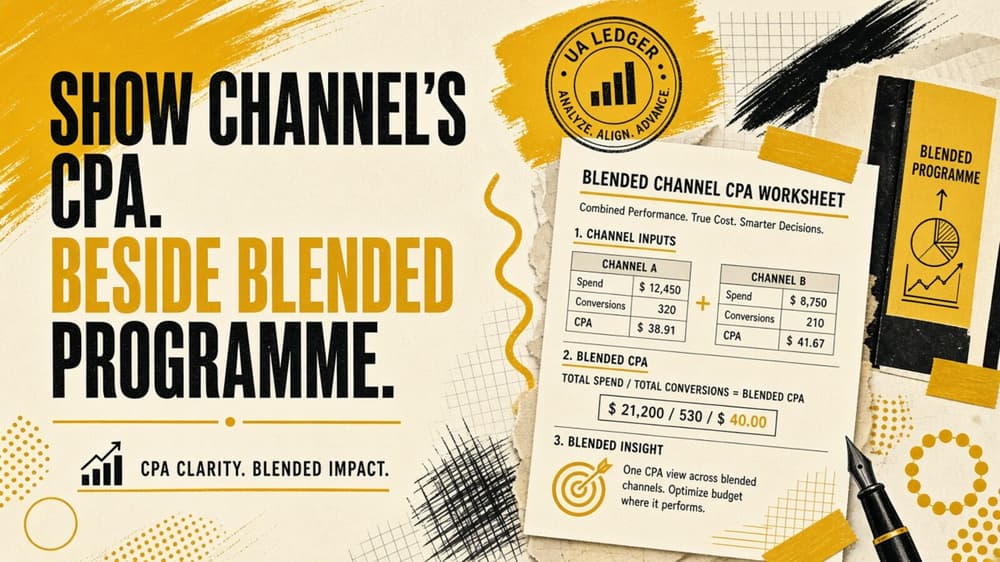
A blended acquisition cost can hide an expensive experiment inside a larger efficient programme. A reproducible illustrative example with editable inputs and explicit limits.
A blended acquisition cost can hide an expensive experiment inside a larger efficient programme. This worksheet adds a proposed channel while preserving the separate channel CPAs. The outcome definition must be identical in both rows before the combined ratio has a useful interpretation.
Define the calculation before using it
Enter spend and comparable outcomes for the existing activity and the proposed channel. Add spend and outcomes before calculating the blend; do not average the two CPAs. Keep proposed outcomes labelled as assumptions until observed, and never mix installs in one row with purchasers in another.
Work through the synthetic example
The existing plan spends 10,000 for 1,000 outcomes; the new test spends 3,000 for 150. Their CPAs are ten and twenty, while the combined figure is about 11.30. The blend is correct arithmetic but cannot support a claim that the new channel itself acquired outcomes for 11.30.
| Output | Worked-example result |
|---|---|
| Existing CPA | 10.0000 |
| New channel CPA | 20.0000 |
| Blended CPA | 11.3043 |
Use the artifact and preserve its assumptions
Open the editable calculator to change the inputs and inspect the sensitivity view. The CSV records synthetic inputs and expected outputs; the JSON fixture keeps the equations available for reproduction. These calculations have been checked against the stated example. No measured campaign data is included.
The sensitivity rows vary only newOutcomes by 20% below and above the entered value. They are scenarios, not confidence limits or a forecast distribution. A row outside the model’s constraints is labelled rather than turned into a plausible-looking result. Save the chosen inputs with the decision so another reader can distinguish a changed assumption from a changed formula.
Evidence and limits
Google describes conversion lag as a reason recent CPA and ROAS can change. The worksheet’s scenario assumptions are supplied by the reader, not generated or endorsed by Google’s forecast system. See About conversion lag reporting, especially “How it works; Campaign types eligible for conversion lag reporting”.
Outcomes must be non-overlapping and comparably measured. Cross-channel overlap, different conversion windows and cannibalisation need reconciliation before allocating from this comparison.
Background: Annual and quarterly UA budget planning and A Q4 UA Budget Planning Checklist Before the Rush. These existing articles provide context; the present calculation does not verify every archived claim.


